Indonesia’s palm oil production is forecast to reach 50.31 million tonnes in 2026, up from an estimated 49.50 million tonnes last year, according to a forecast presented by researcher Rizki Amalia of the Indonesian Oil Palm Research Institute (PPKS) and reported by InfoSawit. The improvement follows a weaker 2024, when output fell to 48.16 million tonnes after a 2023 drought hit yields across the country’s plantation belt.
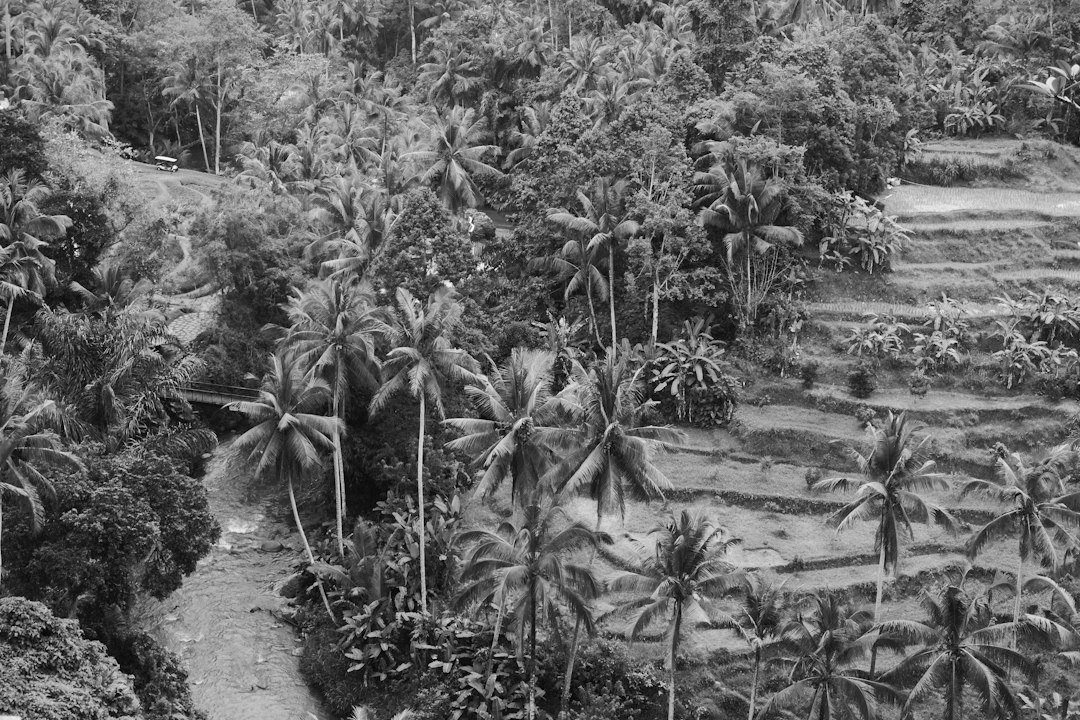
Smallholders hold about 6.9 million hectares of Indonesia’s roughly 16.83 million hectares of palm oil plantation area, more than two-fifths of the total planted area, making their replanting pace a significant factor in the national output forecast. Between 2016 and 2025, the government oversaw the replanting of about 384,618 hectares, covering 169,494 smallholders, with roughly Rp10.86 trillion (around 540 million GBP) disbursed in support by May 2025.
PPKS researchers point to a combination of factors behind the expected rise: recovery from the 2023 drought, higher fertiliser application as fertiliser prices have eased, and productivity gains tied to the accelerated replanting programme. The institute’s presentation, delivered at the 2026 Plantation Commodity Outlook in Bogor, described the industry as still having room for growth despite persistent challenges.

Aging trees remain a risk
Despite the positive forecast, researchers flagged a structural risk: a growing share of Indonesia’s oil palms are now old or senescent, and bringing production levels back up over the long run will depend on how quickly those low-yielding trees are replaced. Replanting is costly and takes years before new trees reach full yield, which is why the government’s financial support scheme for smallholders remains central to the sector’s outlook.
Separately, Indonesian authorities have been exploring sustainability certification schemes aimed specifically at oil palm smallholders, according to Eco-Business, as buyers in Europe and elsewhere increasingly demand traceable, deforestation-free supply chains. Certification costs have historically been a bigger burden for smallholders than for large plantation companies, and officials say a tailored scheme could help smaller growers keep access to export markets.
Balancing output growth with land pressure
Indonesia remains the world’s largest palm oil producer, and its output decisions ripple through global vegetable oil markets used in everything from cooking oil to processed food and biodiesel. The government has framed its 2026 policy priorities around productivity, downstream processing and smallholder empowerment rather than further expansion of planted area, a shift from the rapid acreage growth of previous decades.
For smallholders themselves, the replanting programme offers a path to higher yields on existing land without clearing new forest, though the multi-year gap between replanting and full production remains a real financial strain for farming families waiting for new trees to mature.
Cooperatives in Riau and North Sumatra, two of Indonesia’s largest palm-growing provinces, have been experimenting with intercropping food crops between young replanted palms to give farmers some income during the years before new trees bear fruit. Officials say expanding such bridging schemes nationally could ease the financial pressure that often causes farmers to delay replanting even when their trees are clearly past peak productivity. With global vegetable oil demand continuing to grow, Indonesia’s ability to lift yields on existing land, rather than expand into new areas, will likely determine how much of that demand it can continue to supply sustainably. Buyers in Europe, where deforestation-linked import rules have tightened in recent years, are watching the replanting and certification programmes closely as a sign of whether Indonesian smallholders can meet stricter traceability requirements without being squeezed out of the supply chain altogether.