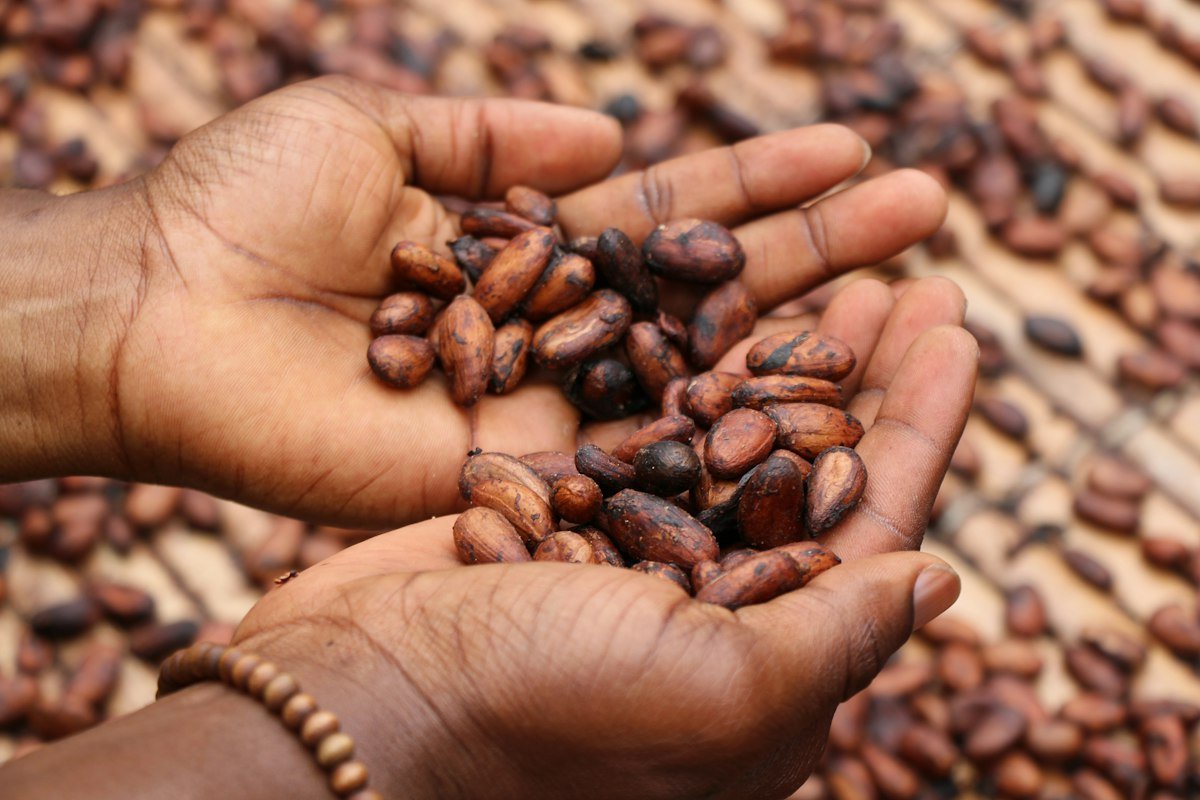
Ghana’s cocoa regulator, COCOBOD, has raised the farmgate price paid to cocoa farmers for the 2026/27 season to GH¢42,400 a tonne, up from GH¢41,392 in the previous season. The rise amounts to about 2.4 percent. It pushed global cocoa futures prices to a two-week high, as traders weighed tighter Ghanaian supply against a weaker national production outlook. The Ghana cocoa farmgate price move keeps farmers’ per-tonne returns rising even as the volume they are expected to produce falls.
The higher Ghana cocoa farmgate price comes as COCOBOD trims its 2026/27 production estimate to around 650,000 tonnes, down roughly 13 percent from an earlier forecast of 750,000 tonnes. The regulator had previously warned that output could fall as low as 450,000 to 550,000 tonnes this season, a far steeper drop than the revised figure now suggests. Even at 650,000 tonnes, the outlook marks a sharp reversal from the growth Ghana’s cocoa sector had been recording only months earlier.
Ghana’s actual 2025/26 harvest reached about 750,000 tonnes, a jump of 25.6 percent from 597,000 tonnes the season before. That rebound followed several seasons in which disease and ageing cocoa trees had dragged down yields across the country. The fresh downgrade for 2026/27, coming so soon after a record recovery, is one that analysts are watching closely for signs of a longer-term slide.

Côte d’Ivoire’s output also slips
Côte d’Ivoire, the world’s largest cocoa producer, has pencilled in 2026/27 output of about 1.8 million tonnes, down from roughly 2.2 million tonnes a year earlier. The decline sits alongside strong recent shipments. Cargoes from its ports between October 2025 and 27 September 2026 totalled about 2.18 million tonnes, nearly 20 percent higher than the same period a year earlier. The contrast between falling output forecasts and rising shipment volumes has added to uncertainty over how tight global supply will actually be.
Analysts pointed to several supply risks weighing on the outlook across both countries. A strengthening El Niño weather pattern threatens rainfall, while crop disease and ageing farms continue to erode yields in Ghana and Côte d’Ivoire alike. These pressures sit alongside strong recent supply and softer demand in some chocolate-buying markets. That combination has kept futures prices swinging within a narrow band, rather than moving in one clear direction.
Price gap raises smuggling concerns
The widening price gap between Ghana and its neighbour has raised concerns about smuggling. Traders worry that cocoa grown in Côte d’Ivoire could be diverted across the border to capture Ghana’s higher farmgate price. Similar price differentials have triggered this pattern in past seasons. Such flows, if they materialise, would complicate efforts to measure each country’s true domestic output this season.
For Ghana’s cocoa farmers, the arithmetic of the new season is mixed. A higher price per tonne lifts the income earned on each bag sold, but a smaller national harvest means there is simply less cocoa to sell overall. COCOBOD has not said how it intends to balance that trade-off. The gap between the price rise and the production downgrade leaves open how much farmer incomes will actually change this season.
Cocoa is one of several African cash crops under pressure this season. East Africa’s coffee sector is facing a comparable squeeze, with Ugandan coffee farmers contending with falling global prices and drought at the same time. Both cases show how climate pressures and shifting global prices are reaching smallholder farmers well before they reach the shelves of chocolate and coffee buyers overseas.